Executive Summary & Quick Verdict
Overall Winner: Plasma One Card
Choose Plasma One if: You want a non-custodial stablecoin card with published cashback tiers, a Lite tier that may be free depending on region, optional yield, and clearly disclosed FX pricing.
Choose Holyheld if: You want a personal IBAN, broader fiat payment rails, multi-network crypto support, and a non-custodial wallet connected to a Mastercard.
The Bottom Line: Holyheld offers a broad global-payments account with stablecoin conversion, card spending, and bank-transfer rails.
Plasma One is the stronger card-first option for users who value published rewards, tiered FX pricing, and a clear stablecoin Earn proposition.
Plasma One vs Holyheld at a Glance
Feature | Plasma One Card | Holyheld |
Card Network | Visa | Mastercard |
Custody Model | Non-custodial (you own and custody your stablecoins) | Non-custodial crypto wallet; card and e-money services provided through partners |
Yield / Return on Balance | Up to 6% variable through Plasma One Earn | Variable APY on USDC through Morpho vaults; no fixed public rate |
FX / Conversion Fees | Lite: ~2% total (1% Plasma + ~1% Visa); Core: ~1.5% total (0.5% Plasma + ~1% Visa); Platinum: 0% FX fee, Visa exchange rate applies | International card payments (outside the EEA): 2.5% + €1 per Holyheld's March 2025 fee schedule; 1% on-ramp and 1% off-ramp fees for individuals |
Crypto-to-Fiat Spread | Not publicly disclosed; tiered on/off-ramp fees apply | No fixed spread published; exchange quote shown before confirmation |
Staking / Lock-In Required | None on Lite; Core: $199/year or 20,000 XPL locked for 12 months; Platinum: 100,000 XPL locked for 12 months | No token lock disclosed for personal membership; Earn withdrawals are flexible |
Annual / Monthly Fees | Lite: $0 (varies by region); Core: $199/year or XPL lock; Platinum: XPL lock only | CHF 0/year for individual membership, by invitation |
Regional Availability | Most countries, excluding 7 restricted countries; 27 US states | Personal membership by invitation; full eligibility not publicly listed. Holyheld's July 2026 terms state they govern users resident in or located in Switzerland |
Fees, rates and limits as of October 2026. Terms vary by region and may change.
The Key Battlegrounds: Plasma One vs Holyheld
1. Yield & Capital Efficiency
Plasma One: Plasma One Earn offers up to 6% variable yield on eligible stablecoins through third-party DeFi protocols. Returns vary with market conditions and protocol performance.
Funds must be moved from Earn back to Cash before they can be spent with the card.
Holyheld: Holyheld offers variable APY on USDC through Morpho vaults. Its app says users can withdraw at any time and use withdrawn funds to top up the card, but current public materials do not state a standard APY.
Plasma One has the clearer published yield proposition. Holyheld still gives users a flexible non-custodial route into Morpho, but readers must check the live rate rather than compare against a fixed public headline.
2. Fees & FX Costs
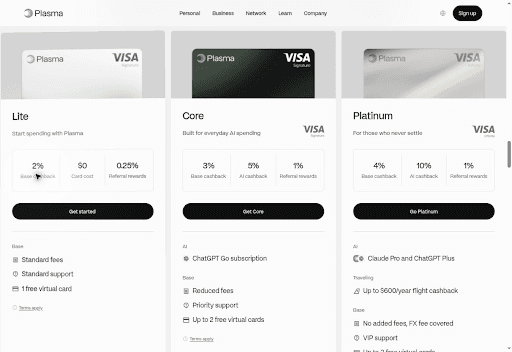
Plasma One: Lite pricing varies by region and may be free, with the applicable price shown in-app. Core costs $199 per year or a 20,000 XPL lock for 12 months.
Plasma's FX markup is 1% on Lite, 0.5% on Core, and 0% on Platinum. Lite and Core also incur Visa network fees typically around 1%, while Platinum converts at the Visa exchange rate with nothing added.
Holyheld: Individual membership costs CHF 0 per year by invitation. Personal on-ramp and off-ramp transfers each cost 1%, while outgoing ACH costs $1, SEPA costs €1, and wires cost $20.
Holyheld's current personal pricing page does not list card fees. Its separate fee schedule, last updated March 2025, lists card issuance fees of €29 to €199 and a 2.5% + €1 fee for international card payments outside the EEA.
Crypto exchanges use a quote that users confirm in the Holyheld app, so final conversion costs depend on the transaction.
On published figures, Plasma One's total card FX cost ranges from about 2% on Lite to 0% on Platinum. Holyheld has no individual membership charge, but its account uses several route-specific transfer and conversion fees.
3. Custody & Control
Plasma One: Plasma One uses a non-custodial stablecoin account. Plasma states that it does not custody the user's stablecoin assets, while card and account infrastructure is provided through partners.
Holyheld: Holyheld also uses a non-custodial crypto model. Its terms say it does not provide crypto custody and that users remain the sole owners of assets in their connected wallets.
Holyheld's debit card and e-money account are provided by regulated partners. Crypto assets stay under user control until an exchange or payment instruction is executed, while fiat card balances follow the partner's terms.
There is no clear winner on crypto custody alone. Both preserve user ownership of crypto assets, but Holyheld more explicitly combines an external wallet with partner-provided fiat and card infrastructure.
4. Rewards, Cashback & Tiers
Plasma One: Base card cashback is currently paid in XPL and steps down across monthly spend bands. Lite pays 2% on the first $500 (then 0.1%), Core 3% on the first $1,000 (then 2%, 1%, and 0.25%), and Platinum 4% on the first $3,000 (then 3%, 2%, and 1%).
Lite pricing varies by region and may be free. Core costs $199 per year or a 20,000 XPL lock, and Platinum requires locking 100,000 XPL for 12 months.
Holyheld: Holyheld's published fee schedule, last updated March 2025, lists 0.5% cashback for Classic and Limited Edition cards and 1% for Metal, paid in USDC. Its current 2026 personal pages do not restate these rates, so users should confirm current availability in-app.
Holyheld does not publicly disclose a token lock for its personal membership. That gives it simpler membership access once invited, while Plasma ties some higher-tier benefits to an annual fee or XPL lock.
Plasma One's starting cashback rates of 2% to 4% are higher than the 0.5% to 1% in Holyheld's published schedule, although Plasma's rates step down as monthly spend rises. Holyheld also advertises travel booking with cashback rewards in its app.
Pros & Cons of Each
Plasma One
Pros:
Non-custodial stablecoin account: Plasma does not custody the stablecoin assets held by the user.
Low-cost entry tier: Lite pricing varies by region and may be free, with 2% base cashback on the first $500 of monthly spend.
Up to 6% variable yield is available through Plasma One Earn.
Cons:
Cashback steps down across spending bands and base card cashback is currently paid in XPL.
Higher tiers add trade-offs: Core can require an annual fee or XPL lock, while Platinum requires XPL locking and Lite/Core carry FX markups.
Holyheld
Pros:
Non-custodial crypto model with a connected wallet, Mastercard spending, and a personal account.
CHF 0 annual individual membership for users accepted through the invitation process.
Broad payment connectivity across stablecoins, 20+ networks, virtual accounts, and bank-transfer rails.
Cons:
Personal access is by invitation, and Holyheld does not publish a complete consumer eligibility list.
Card fees and cashback rates come from older schedules (2023 to 2025) that current personal pages do not restate, and no current card-spending limit schedule is published.
Several money-movement fees apply, including 1% personal on-ramp and off-ramp charges plus fees on outgoing ACH, SEPA, and wires.
Why Choose Plasma One Over Holyheld?
Plasma One is the stronger choice for card spending on the published numbers. Its starting cashback (2% to 4%) is higher than Holyheld's published 0.5% to 1%, and its total card FX cost runs from about 2% on Lite to 0% on Platinum.
Holyheld's dated fee schedule lists 2.5% + €1 on international card payments. Plasma One also publishes its tier pricing and a variable Earn rate of up to 6%, so the cost and reward trade-offs are visible before joining.
Holyheld is attractive for users who want a personal IBAN, broad onchain connectivity, and multiple bank-payment rails. Its non-custodial crypto model also lets users connect existing wallets rather than move assets into a custodial crypto account.
Final Verdict & How to Upgrade
If you want a personal account with ACH, SEPA, wires, broad network support, and non-custodial wallet connectivity, Holyheld is a strong option for users who can secure an invitation.
For users focused primarily on stablecoin spending, higher published cashback, and lower published card FX costs, Plasma One is the better overall choice. Holyheld leans further into global account functionality.
How to Get Started With Plasma One
Apply for Your Card: Create a Plasma One account, complete the required identity checks, and choose the Lite, Core, or Platinum tier that fits your needs.
Deposit Stablecoins: Fund your non-custodial Plasma One account and allocate eligible stablecoins to Earn if you want variable yield exposure.
Start Spending: Activate your Plasma One Visa card, add it to a supported mobile wallet if desired, and use it for eligible everyday purchases.
Ready to get started? Claim your Plasma One card